11 October 2026


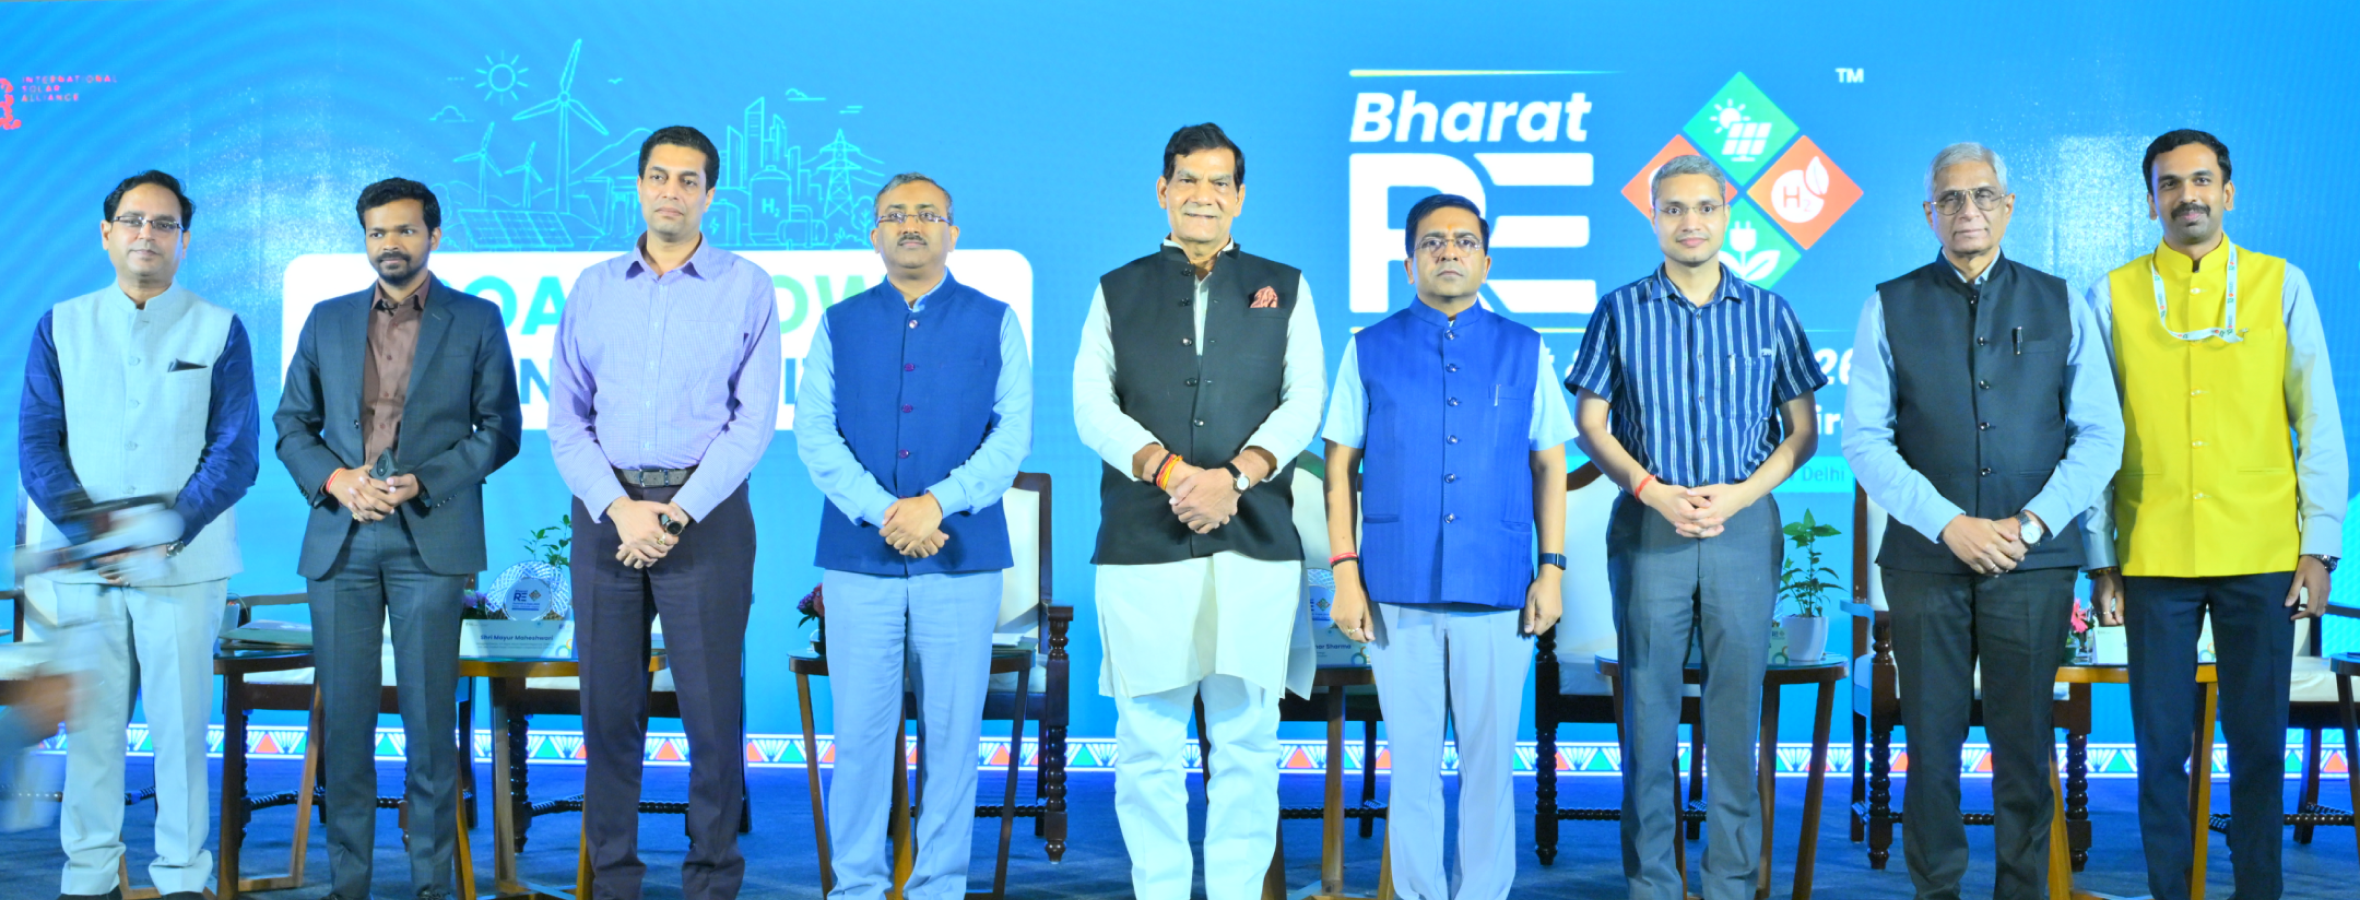
Shri Vishal Raj, IAS
Managing Director, Bihar State Power Generation Company Limited (BSPGCL)
Shri Vishal Raj used Bihar’s recent power-sector turnaround to challenge older perceptions of the state and make a direct investment case for its next phase of growth.
He said Bihar’s DISCOMs were now profit-making and among the country’s better-rated utilities, with AT&C losses brought down to 11.5%, while the transmission company was also profitable and being considered for listing.
Peak demand has reached around 9.5 GW, a multi-fold increase from 2014. Raj linked that growth to rising consumer numbers and rapidly increasing per-capita electricity consumption, while noting that consumption still remains below the national average—leaving significant headroom for future demand.
He also cited Bihar’s supply standards of around 22 hours in rural areas and 24 hours in urban areas as part of the infrastructure base supporting that demand growth.
Storage featured prominently in his presentation. At Kajra in Lakhisarai district, he referred to a project combining around 185 MW of solar generation with 282 MWh of battery storage, with plans to scale storage to about 500 MWh around January 2027 and to 1,000 MWh by the end of 2027.
Bihar has also solarised around 13,000 government buildings, representing about 120 MW of rooftop solar, while an additional 500 MW is being taken up.
On pumped storage, Raj said two projects were already being surveyed and that an expression-of-interest exercise had surfaced around 6,000 MW of additional opportunity. Taken together, he put the near-term pumped-storage opportunity at roughly 8,400 MW.
The investment pipeline is equally significant. Raj referred to a minimum planned investment of around ₹1.38 lakh crore over the next five years, describing even that figure as conservative given Bihar’s demand trajectory and its gap with the national average.
His invitation to investors rested on a simple argument: where present penetration is lower but demand is rising quickly, the scope for new generation, storage and infrastructure can be larger.
The Bihar story at Lucknow was therefore not only about 11.5% AT&C losses and 9.5 GW peak demand; it was also about storage, public-sector solarisation, improving utilities and a sizeable investment pipeline.